Understanding the Two-Stage Deadline Process
The two-stage process for tax compliance is crucial for businesses to effectively navigate the requirements associated with tax deadlines in September and October. This process not only helps in organizing financial responsibilities but also ensures adherence to legal obligations, minimizing the risks of penalties or audits. The first stage generally involves the preparation and submission of tax audit reports, which must be completed ahead of the corresponding deadline. During this phase, accuracy in reporting income and expenses is critical, as discrepancies can lead to complications in later stages.
In many jurisdictions, businesses are required to submit various tax returns that may include corporate taxes, payroll taxes, and value-added tax (VAT) reports. The deadline for these submissions often falls within the months of September and October, highlighting the importance of timely action. Failure to meet these deadlines can result in financial consequences, such as interest on unpaid amounts and potential fines. Thus, understanding the specifics of the two-stage deadline process allows businesses to allocate appropriate resources to ensure compliance.
Furthermore, the second stage typically involves any necessary corrections or adjustments following the receipt of confirmations or notices from tax authorities. During this phase, businesses must remain vigilant for any feedback regarding their submissions, which can necessitate further action. A clear comprehension of the implications of these deadlines is essential; it can influence financial planning and cash flow management. Businesses should cultivate an internal culture that prioritizes timely submissions to safeguard against compliance issues. By adopting effective strategies and tools for monitoring these deadlines, organizations can foster financial health and regulatory compliance simultaneously.
The Importance of Tax Audit Reports
Submitting tax audit reports, specifically forms 3CA, 3CB, and 3CD, by the September 30 deadline is crucial for businesses seeking to adhere to regulatory compliance standards. These reports serve as significant documentation that verifies a company’s financial activities and ensures that its accounts are in order. Tax audits are not merely administrative tasks; they are a reflection of a business’s transparency and accountability towards its stakeholders and regulatory bodies.
The primary purpose of these tax audit reports is to provide a true and fair view of a company’s financial health. By conducting a thorough audit, businesses can identify discrepancies and ensure accurate representation of financial data. This accuracy is not only beneficial for fulfilling tax obligations but also critical in enhancing the trust of investors, clients, and regulatory authorities. It minimizes the risk of future penalties and rejections during tax assessments, which can arise from discrepancies or inconsistencies in financial reporting.
Moreover, timely submission of these audit reports plays a significant role in maintaining smooth operations within a business. Delays or failures in filing can lead to serious repercussions, such as financial penalties, increased scrutiny from tax authorities, and, in some instances, legal action. Companies may face audits or investigations due to non-compliance, which could disrupt their business activities and harm their reputations. Hence, meeting the deadline for tax audit report submissions is not just a matter of compliance; it is a strategic decision that safeguards a company’s long-term operational integrity.
In conclusion, the necessity of adhering to the September 30 deadline for tax audit reports cannot be overstated. Businesses that prioritize this requirement not only comply with legal obligations but also enhance their credibility and operational efficiency.
Checklist for Submitting Tax Audit Reports
Submitting tax audit reports can be a meticulous process for businesses, particularly as deadlines approach. To ensure compliance and smooth submission, it is crucial to follow a comprehensive checklist. The following steps will guide businesses through the necessary actions for preparing and submitting tax audit reports accurately and on time.
First, begin by gathering all relevant documentation. This includes financial statements, tax returns from previous years, and supporting documents such as invoices and receipts. Ensure that all these documents are accurate and well-organized, as this will serve as the foundation for your audit report. Maintaining clear records throughout the year can simplify this process significantly.
Next, engage with your accounting or finance department to review the prepared documentation. This step is essential for validating the figures reported and ensuring that all necessary information has been captured accurately. Any discrepancies should be addressed immediately to prevent delays in the submission process.
Once the documentation is reviewed and confirmed, the approval process should commence. This typically involves higher management or designated approval authorities within your organization. Ensuring that all stakeholders are informed and their approvals obtained is vital for a timely submission of tax audit reports.
Furthermore, familiarize yourself with the specific deadlines associated with tax audit submissions, as these can vary based on jurisdiction and the nature of your business. Mark these dates in your calendar well in advance to create ample time for preparation and submission. It is advisable to create reminders as the deadlines approach, keeping your team on track.
Finally, after submitting your tax audit report, ensure that you keep copies of all filed documents and confirmations. This will be beneficial for future audits or inquiries from tax authorities. By following this checklist, businesses can navigate the complexities of tax audit reports with greater ease and adherence to compliance standards, ultimately minimizing the risk of penalties or additional scrutiny from tax agencies.
Common Mistakes to Avoid in Tax Audits
Tax audits can be daunting for many businesses, yet understanding common pitfalls can help mitigate the stress and potential consequences. One of the most prevalent mistakes is the misfiling of reports. This can occur when businesses inadvertently submit incorrect forms or fail to file essential documents within the mandated deadlines. Such errors can lead to further scrutiny and potentially significant financial penalties. Ensuring that all forms are accurately completed and submitted on time is crucial in maintaining compliance during an audit.
Inadequate documentation is another major issue that often arises during tax audits. Businesses must maintain thorough and organized records that support their income, expenses, and deductions. Missing invoices or receipts can create discrepancies that auditors may view as intentional misrepresentation. Therefore, companies are advised to implement a robust record-keeping system that encompasses all pertinent financial information. This not only aids during an audit but also contributes to better financial management overall.
Moreover, overlooked deadlines present a significant risk, as late submissions can result in penalties and interest charges. Many businesses lose track of important dates due to various operational pressures. To counter this, it is recommended that companies establish a compliance calendar to keep track of key deadlines throughout the year. Such proactive measures not only ensure timely submissions but also foster a culture of accountability within the organization.
Additionally, when businesses do not adequately prepare for potential audits, they may experience unnecessary stress and complications. Regular self-audits can help organizations stay on track. By identifying and addressing discrepancies ahead of time, businesses can fortify their positions and minimize the risks associated with audits. In conclusion, by paying close attention to the aforementioned common mistakes, businesses can significantly enhance their preparedness for tax audits and ensure smoother compliance processes.
Preparing for Financial Reconciliation
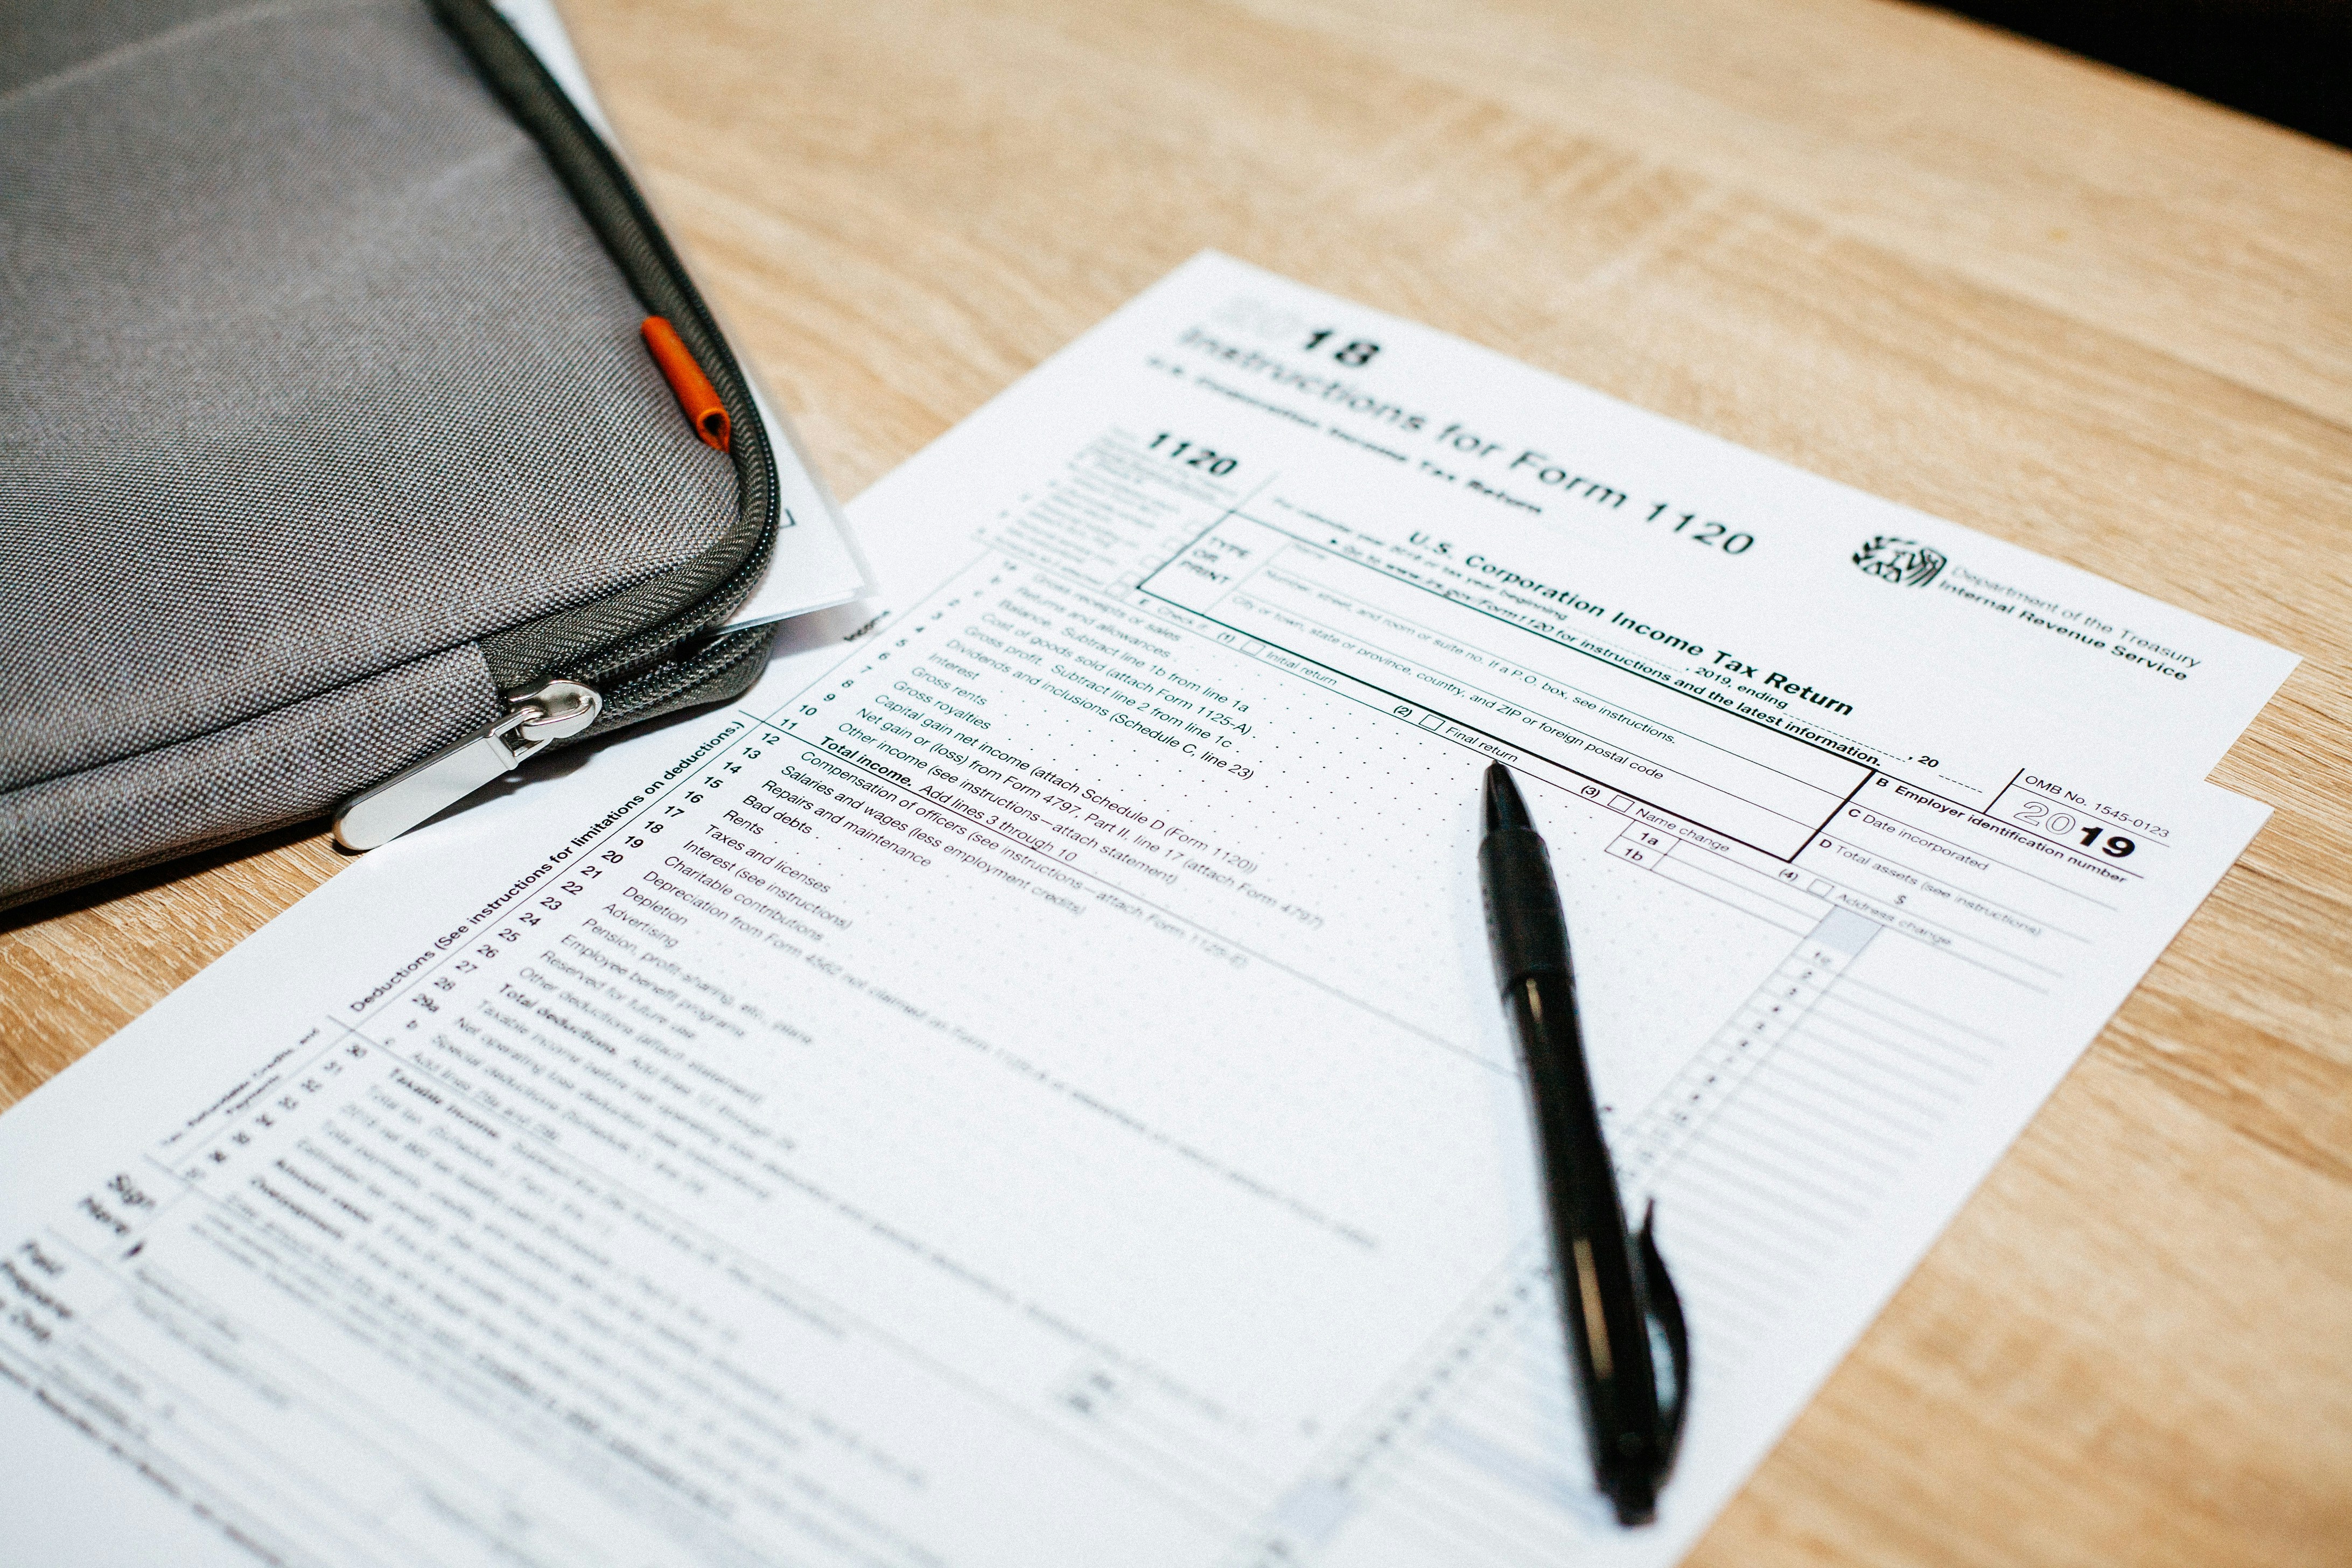
Financial reconciliation is a crucial step in the management of an organization’s financial reporting, particularly in the period leading up to tax deadlines. As organizations approach the Income Tax Return (ITR) deadline, the significance of reconciling audited financial statements cannot be overstated. This process not only helps ensure compliance with tax regulations but also enhances the overall accuracy and reliability of financial data.
The first step in preparing for financial reconciliation involves gathering all relevant financial documents. This includes the trial balance, audited financial statements, and any supplementary schedules. Each of these documents provides vital information necessary for verifying the completeness and correctness of financial records. A thorough review of these documents will aid in identifying any discrepancies that need to be addressed before submission.
Next, it is essential to compare the financial reports against bank statements and other reconciliatory documents. This step ensures that all transactions have been accurately recorded and provides an opportunity to resolve any variances. It is advisable to concentrate on high-volume accounts first, as these often hold the largest discrepancies. Additionally, documenting the reconciliation process offers a transparent trail of the actions taken, should any questions arise in the future.
Furthermore, engaging with a qualified professional or auditor could offer an added layer of assurance. Their expertise can help identify potential financial misstatements that may need correction prior to the ITR deadline. It is important not to overlook the implications of these financial reconciliations; inaccuracies can lead to substantial penalties or delays in tax processing. Preparing for financial reconciliation should therefore be viewed as a strategic necessity, enabling organizations to maintain fiscal health and compliance.
The Role of Auditors in Financial Reconciliation
Auditors play a crucial role in the financial reconciliation process, ensuring that businesses maintain accuracy and integrity in their financial statements. They serve as independent evaluators, providing an objective assessment of an organization’s financial records and practices. This process is vital for businesses, especially when preparing for tax season, as it helps in identifying discrepancies that could lead to financial liabilities or compliance issues.
During the reconciliation process, auditors review various financial documents, including balance sheets, income statements, and cash flow statements. Their expertise allows them to identify inconsistencies or errors that might go unnoticed by internal accounting teams. Additionally, auditors use various techniques and tools to validate the accuracy of financial data, thereby reinforcing the trustworthiness of the reported information.
To collaborate effectively with auditors, businesses should maintain organized financial records and provide full access to necessary documentation. This transparency not only facilitates a smoother audit process but also helps resolve any potential misunderstandings. Furthermore, regular communication with auditors can help establish a productive relationship, ensuring that any concerns or questions are addressed promptly.
Understanding the role of auditors in financial reconciliation is essential for any business aiming for accurate financial reporting. Engaging with auditors proactively can enhance the quality of financial statements and potentially reveal areas for improvement in internal controls and financial management practices. By fostering an environment of transparency and openness, businesses can significantly benefit from the insights provided by auditors during the reconciliation process.
In conclusion, the collaboration between businesses and auditors is vital for achieving accurate financial reconciliation, which not only supports compliance during tax season but also strengthens overall financial health.
Deadlines and Timelines: What You Need to Know
Staying abreast of tax deadlines is crucial for businesses aiming to maintain compliance and avoid penalties. For the months of September and October, a detailed timeline of key dates is essential to keep your tax obligations in check. Understanding these timelines will aid in ensuring your business remains within the legal parameters set by the tax authorities.
First and foremost, September 15 marks a significant deadline for partnerships and S corporations. These entities are required to file their tax returns for the previous fiscal year. This deadline is mandatory for those who have opted for an extension, so it is advisable to prepare necessary documentation well in advance to ensure timely filing.
Continuing through September, September 30 is another noteworthy date, particularly for employers who need to file Form 941, which is the Employer’s Quarterly Federal Tax Return. This form outlines employee wages and withheld taxes, making its timely submission critical to maintain compliance with federal regulations.
October brings a series of essential deadlines as well. October 15 is a crucial date for C corporations which must file their tax returns if they have received an extension. Similar to partnerships and S corporations, it is vital that these businesses prepare in advance to comply with filing requirements. Failure to submit by this deadline can result in significant penalties.
Additionally, if you are a corporation employing estimated tax payments, the deadline to pay your third installment for the year falls on October 15. Ensuring that these payments are made will aid in maintaining your tax compliance and alleviating future financial burdens.
Therefore, having a well-structured timeline for these crucial dates not only ensures compliance but also enhances the operational efficiency of your business during these months. Proper planning and organization around these deadlines will facilitate a smoother tax process and mitigate any potential issues with tax authorities.
Penalties for Non-Compliance: What to Watch For
In the realm of business taxation, non-compliance with mandatory tax audit report submissions and financial reconciliations can lead to severe consequences. Companies that fail to adhere to established deadlines and regulations risk incurring significant penalties that can adversely affect their financial standing and reputation. It is imperative for businesses to understand these potential repercussions in order to maintain compliance and avoid unnecessary complications.
Firstly, one of the most immediate consequences of non-compliance is the imposition of monetary penalties. These financial fines can vary significantly based on the nature and severity of the non-compliance. For instance, late filings may incur fines which escalate the longer the delay persists. As a result, businesses may find themselves facing mounting costs simply for failing to meet compliance deadlines.
Moreover, consistent non-compliance could lead to audits and scrutiny from tax authorities. A business that frequently fails to submit accurate reports or reconcile its finances appropriately may draw the attention of regulatory bodies, which could result in even more rigorous investigative measures. These audits can be time-consuming and resource-intensive, detracting from the organization’s core operations.
In addition to financial penalties, non-compliance can harm a business’s credibility and trustworthiness. Clients, partners, and investors may become wary of engaging with companies that have a track record of evading compliance requirements, thus negatively impacting potential business opportunities. Maintaining regulatory compliance is crucial not only for avoiding fines but also for fostering strong relationships with stakeholders.
Furthermore, repeated instances of tax-related non-compliance can lead to legal consequences. Businesses may face litigation or more severe penalties if they disregard compliance requirements consistently. Therefore, understanding the full range of penalties for non-compliance is essential for businesses aiming to navigate the complex landscape of tax regulations effectively.
In conclusion, the risks associated with non-compliance encompass monetary fines, increased scrutiny from regulatory authorities, loss of credibility, and potential legal issues. As such, it is vital for businesses to prioritize adherence to tax audit report submissions and financial reconciliations to mitigate these risks and ensure a stable operational environment.
Resources for Further Assistance and Compliance Tools
In the realm of tax compliance and navigating deadlines, it is crucial for businesses to leverage various resources and tools that can facilitate the process. Ensuring compliance with the myriad of regulations requires diligent management and the right set of instruments. Below are several key resources that can assist in this endeavor.
Firstly, utilizing accounting software such as QuickBooks or Xero can greatly simplify tracking income, expenses, and compliance-related paperwork. These platforms often come equipped with features that allow for tax calculations and generating reports essential for audits. Such tools can reduce the margin for error and save valuable time during the tax season.
Additionally, many professional accounting firms and tax consultants offer services specifically designed for audit preparation and compliance assurance. Engaging with a Certified Public Accountant (CPA) can provide invaluable guidance on maintaining compliance with federal, state, and local tax regulations. They can also help businesses stay informed about changing laws and deadlines pertinent to their operations.
Moreover, various online webinars and courses offered by institutions such as the American Institute of CPAs (AICPA) provide updated educational content on tax law changes and compliance strategies. These resources can enhance the knowledge base of both business owners and their accounting teams, empowering them to make informed decisions.
Finally, online communities and forums such as those found on Reddit or specialized LinkedIn groups, focusing on business compliance, can be excellent platforms for sharing experiences and obtaining advice from fellow business owners and industry experts. These engagements can lead to valuable insights into best practices for maintaining compliance and preparing for audits.
In conclusion, employing a combination of technology, professional expertise, educational resources, and community engagement can significantly aid businesses in navigating compliance requirements and audit processes. It is essential to take proactive measures by integrating these resources into a comprehensive compliance strategy to ensure smooth operations.
